Topic 2: DEBT: CLOUDY SKIES
In September 2026, India's debt market came under broad pressure, with yields rising across government securities (G-secs), corporate bonds and money-market instruments before a partial recovery late in the month. The move was driven by higher crude oil, a global bond sell-off led by US Treasuries, sticky inflation, expectations of a hawkish Reserve Bank of India and heavy domestic bond supply, the same forces that hurt equities during the month. In the government bond market, the benchmark 10-year yield rose from roughly 6.95% to 7.00% at the start of September to a peak near 7.18%, a two-year high, in late September. It then eased slightly to about 7.15% to 7.17% by month-end. That amounted to a rise of about 20 to 25 basis points over the month, and about 43 basis points since the end of June, when the yield stood at 6.74%. Large domestic auctions, including one of 340 billion rupees, drew robust demand but still cleared at higher yields, and the benchmark 6.94% 2036 gilt touched about 7.14% intraday at one point. Four factors explain the move. First, Brent crude above 105 to 108 dollars raised imported inflation and fiscal concerns. Second, the US 10-year yield near 5.2%, its highest in about two decades, triggered a global bond rout that lifted Indian yields through risk-premium and carry channels. Third, August CPI inflation of 4.82% and a recent Fed hike strengthened expectations that the RBI would raise rates, with the market pricing an increase at the October 7 meeting. Fourth, heavy government borrowing, including an H2 FY27 gross borrowing plan of 7.86 trillion rupees and large weekly auctions, kept supply in focus, even though the government trimmed the share of 5- and 10-year papers to steady the curve. As a result, G-sec prices fell, and yields rose, with a modest pullback near month-end on a slightly softer oil and borrowing mix. Corporate bond yields also edged higher, tracking the G-sec move, but spreads over G-secs widened as investors demanded extra compensation for volatility. Banks and other institutions stepped up participation in high-quality corporate paper because the wider spread offered better carry than gilts. New issuance continued, including from REITs and NBFCs, but pricing reflected the higher rate environment, and some deals used floating-rate structures to manage duration risk. Corporate behaviour followed from several causes: the pass-through of higher risk-free rates lifted the whole curve, so issuers had to pay higher absolute yields. Global risk aversion, FII equity selling and oil and inflation worries raised term and credit premiums, particularly for lower-rated names. At the same time, banks rotated some allocation into investment-grade corporates for extra yield, which supported primary issues. The net effect was higher absolute yields and wider spreads, but demand for good credits. In the money market, the call money rate hovered near the RBI's standing deposit facility rate of about 5.00%, reflecting ample system liquidity despite large advance-tax outflows of roughly 1.7 trillion rupees. Short-tenor yields firmed, with the 364-day T-bill auction cut-off rising to about 6.04%, the highest since April 2025, which signalled higher pricing at the short end. RBI open market operations, including gilt sales, and tax outflows created episodic tightness, but liquidity stayed in surplus overall and capped any sharp spike in overnight rates. The main reason for the short-end move was the market's expectation of a near-term policy rate hike, since inflation sits above the RBI's 4% target and global central banks are hawkish. This lifted short-end yields even while liquidity was comfortable, and the tax-related drain was too temporary to cause sustained stress.
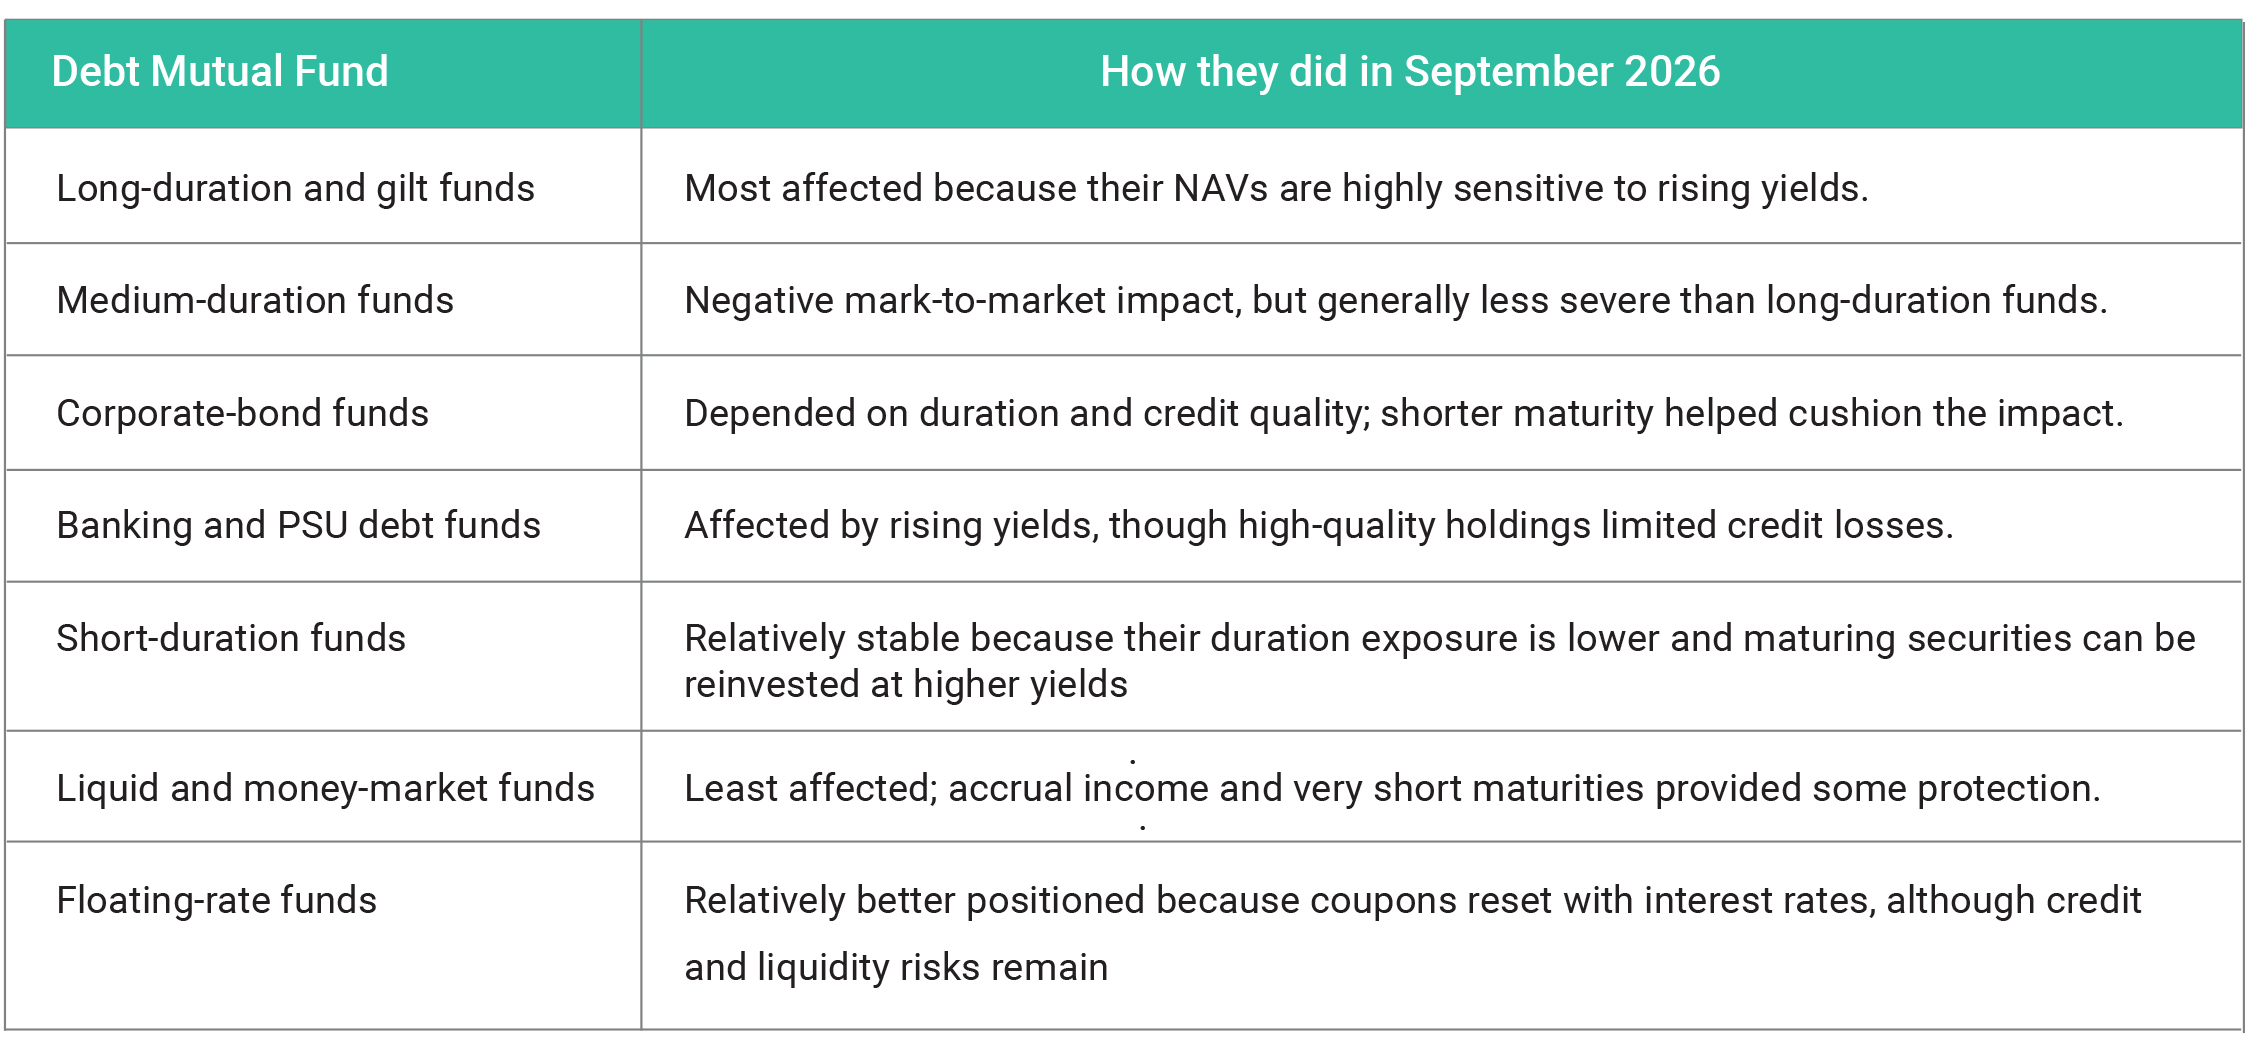
Taken together, the segments tell a consistent story. G-secs saw yields rise by about 20 to 25 basis points to roughly 7.15% to 7.17%, driven by crude above 105 dollars, US yields near 5.2%, the 4.82% CPI print, rate-hike expectations and heavy supply. Corporate bonds saw higher yields and wider spreads, with banks rotating into investment-grade names as G-sec pass-through and higher term and credit premiums played out. The money market saw higher short-end yields, with the 364-day T-bill near 6.04% and call money steady near 5.00%, as inflation and global hawkishness fed rate-hike pricing while ample liquidity limited volatility. The overall picture is of a debt market repricing for a more hawkish policy path, with the partial late-month recovery in G-secs offering only modest relief.