Topic 6: MUTUAL FUND: SNAPSHOT
The headline story for Indian mutual funds in October
2026 was resilient retail SIP-led inflows amid market
volatility and a slowdown in discretionary equity buying.
The industry’s quarterly average AUM rose to ₹89.51 lakh
crore in Q2 FY27, while October equity deployment
moderated and debt funds continued to see outflows.
India’s mutual fund industry witnessed moderating equity
investments in October, with net equity purchases falling
to ₹43,024 crore, a three-month low, although cumulative
deployment in 2026 reached ₹4.7 trillion. Retail
participation remained resilient, supported by record
September SIP contributions of ₹32,490 crore and 10.89
crore SIP accounts. Quarterly average AUM rose 4.9%
sequentially and 14.1% year-on-year to ₹89.51 lakh crore
in Q2 FY27. Market volatility, a global technology-led
sell-off, a stronger US dollar and higher interest-rate
expectations encouraged investors to adopt a cautious
approach towards equities, particularly mid-cap and hybrid
funds. Debt funds faced seasonal redemptions of ₹1.83 lakh
crore in September, driven by treasury and corporate
liquidity requirements. However, corporate bond funds
attracted ₹15,051 crore in October, their highest inflow in 19
months. Gold ETFs also gained traction, with AUM reaching
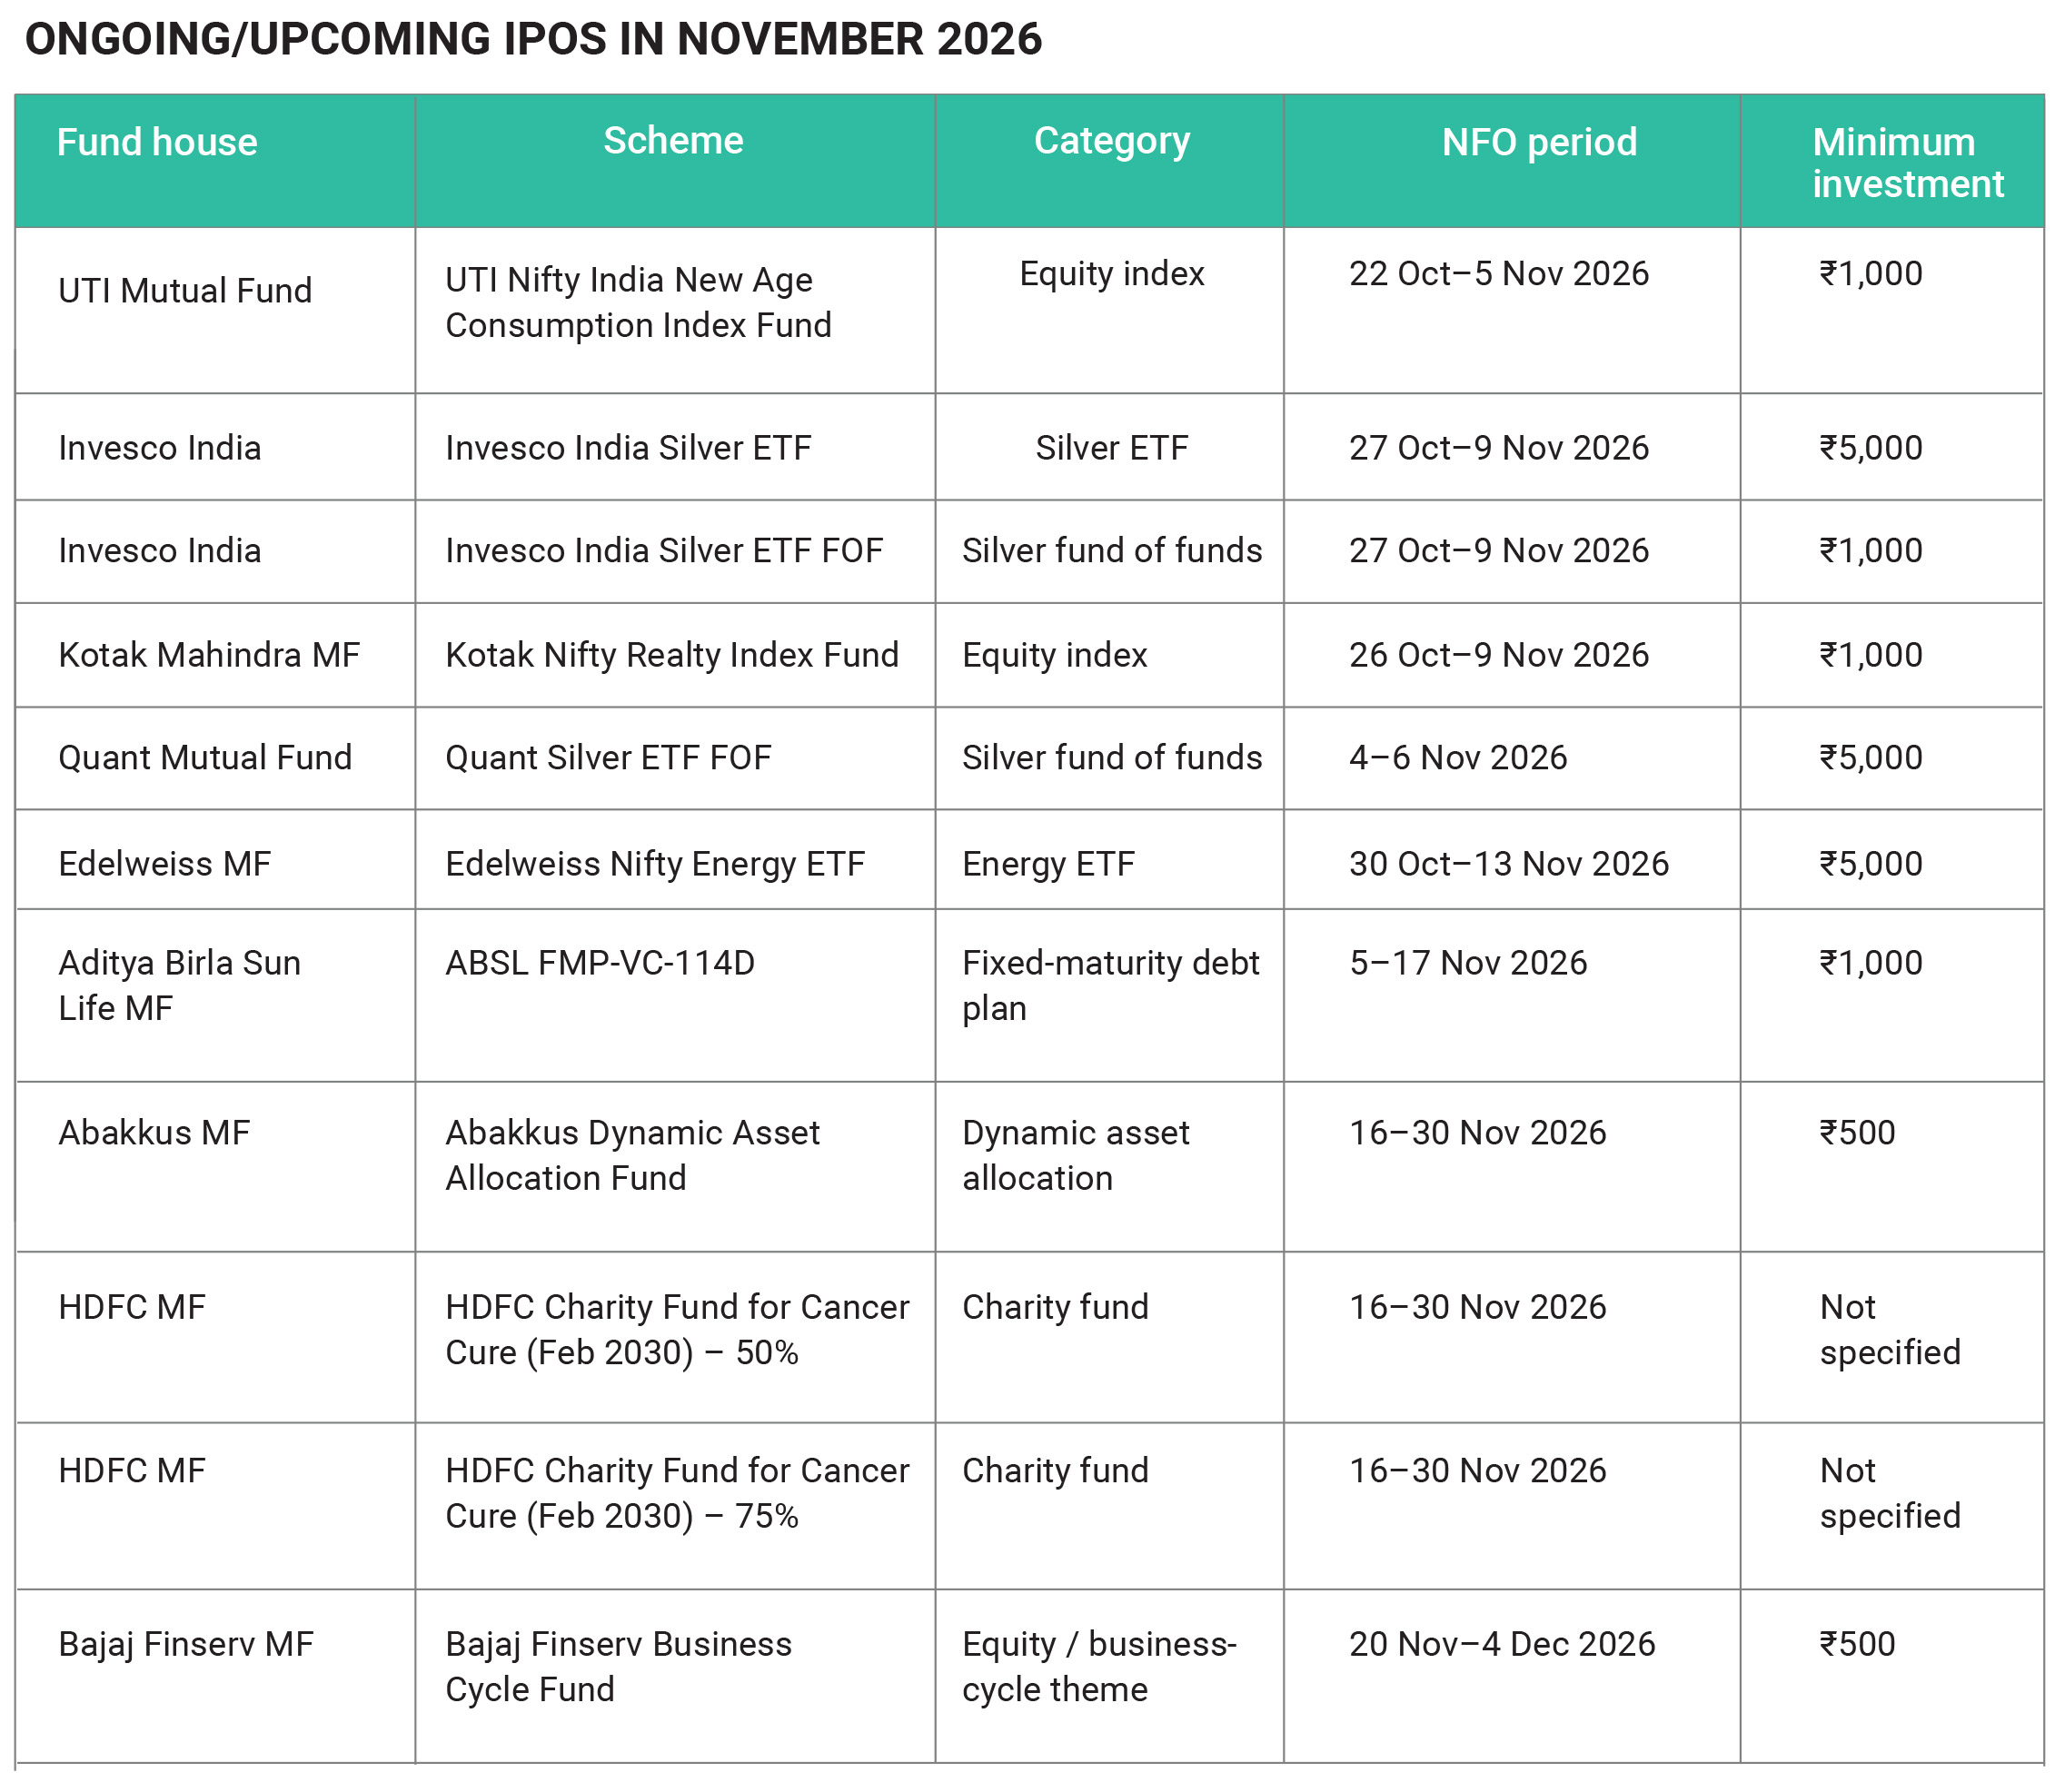
₹1.91 lakh crore, while Carnelian’s maiden small-cap NFO
mobilised ₹632 crore. Overall, investors increasingly
favoured selective equity exposure, corporate bonds and
gold amid market uncertainty.
INSURANCE: WRAP
India’s insurance sector witnessed significant regulatory
developments in October 2026, led by IRDAI’s proposed
overhaul of insurance distribution economics. The regulator
considered reintroducing product- and channel-specific
commission caps, alongside lower
expense-of-management limits, drawing concerns from
brokers and NBFCs over potential revenue losses. IRDAI
also expanded insurers’ investment options to include
private companies, infrastructure SPV debt and
securities-lending transactions, subject to safeguards. In
health insurance, the regulator upgraded its Business
Analytics Platform to streamline regulatory reporting and
product administration, while strong demand supported
a 46% year-on-year rise in new health premiums. IRDAI
also cautioned against higher customer co-payments and
dynamic pricing practices. Following flood-related
disruptions, insurers were directed to expedite claims,
deploy surveyors and establish dedicated assistance
facilities. Additionally, the regulator emphasised curbing
mis-selling through incentives linked to policy persistence
rather than initial sales. Ather Energy’s subsidiary also
received registration as a composite corporate insurance
agent, enabling distribution across life, general and health
insurance.